

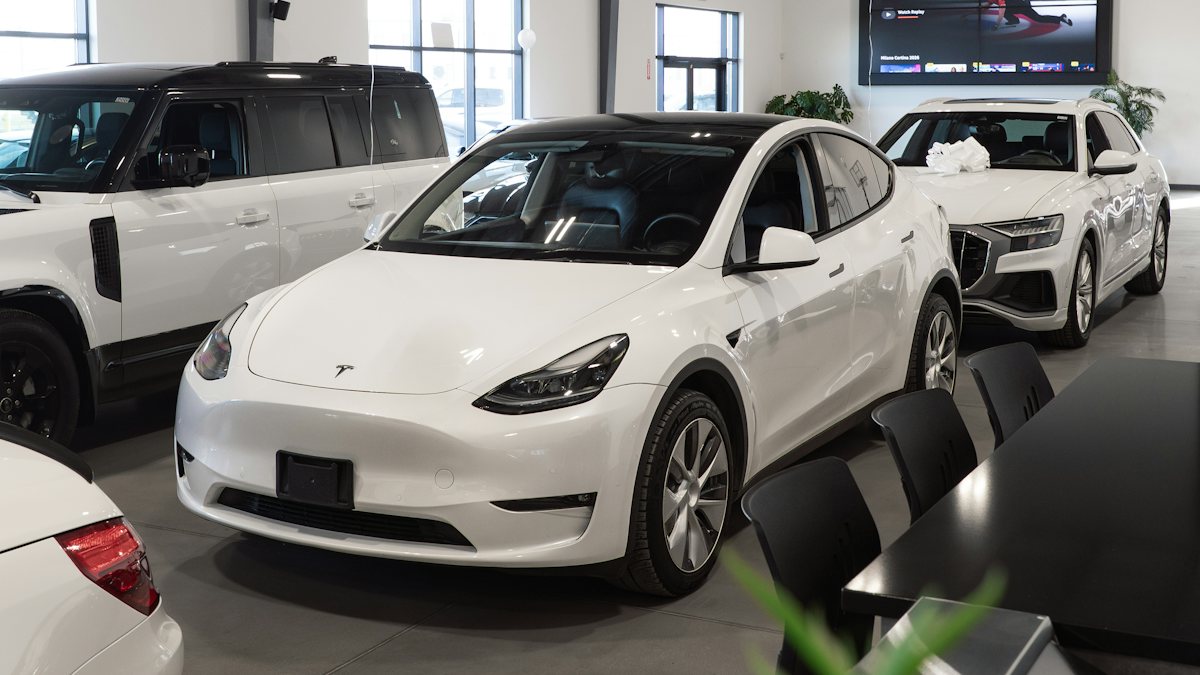
Quick answer: You can usually buy personal auto insurance for a used electric car in the United States, but the coverage available and the price depend on the exact VIN, vehicle model, driver, location and condition. A pre-owned EV with a clean title may be straightforward to quote, while a salvage or rebuilt title can narrow insurer options or physical-damage coverage. Before purchasing, check the title and loss history, open recalls, remaining battery-warranty terms and a written insurance quote.
Scope: U.S. pre-owned battery-electric vehicles (BEVs), reviewed November 7, 2026. Insurers and state motor vehicle agencies follow different rules; this guide does not promise that any particular car will qualify for a policy or coverage limit.
Is it harder or more expensive to insure a used electric car?
Not necessarily. The National Association of Insurance Commissioners (NAIC) identifies vehicle values, parts supply, specialist repair requirements and battery-related costs among factors that can affect EV pricing. However, being used or battery-powered does not by itself establish a universal surcharge. A lower market value may affect a car’s insurance cost, but replacement parts, claim history and insurer underwriting still matter.
Ask for a quote on the specific vehicle identification number (VIN). A VIN-based quote is more useful than a generic estimate for a model name: model year, options, trim and vehicle history can affect underwriting and potential claims. Compare the same driver, address, annual mileage, liability limits, collision and comprehensive deductibles across insurers. For a detailed method, see our US EV insurance cost and quote checklist.
Don’t assume “older EV” always means cheaper cover: the vehicle may have specialist components, an uncommon battery pack or a limited local repair network. At the same time, lower vehicle values may make some premiums more competitive. Only an actual written offer can resolve the trade-off.
Check title history before purchasing insurance
The U.S. Federal Trade Commission (FTC) advises shoppers to obtain a vehicle history report before buying. Use the National Motor Vehicle Title Information System (NMVTIS) to access approved providers that can report title brands, insurance-loss and salvage history. A report may be subject to a fee. Depending on the provider, other reports may contain accident or repair data.
| Used EV situation | Insurance question | What to verify first |
|---|---|---|
| Clean title, ordinary prior use | Are the desired liability, collision and comprehensive coverages available? | Confirm the actual VIN, current title and written quote. |
| Salvage title | Will the insurer cover the vehicle, and will it offer physical-damage protection? | Ask about title status, legal road use, inspection rules and insurer eligibility. |
| Rebuilt or reconstructed title | Are there coverage limitations, higher excesses/deductibles or special valuation rules? | Provide repair documentation and verify state registration requirements. |
| Recorded flood or previous total loss | What existing damage is excluded and how will value be calculated after a new claim? | Obtain the title history, independent inspection and insurer’s written answer. |
| Financed used EV | Does the lender require collision and comprehensive insurance? | Compare lender requirements with the offered policy before closing. |
Critical distinction: A clean title and an uneventful history report do not prove the vehicle has never sustained damage; a report is also not a substitute for an independent inspection. The FTC explicitly recommends both a history report and an independent inspection.
Can you insure a salvage-title or rebuilt electric vehicle?
There is no uniform nationwide rule guaranteeing coverage. Some carriers may offer liability-only insurance on a qualifying rebuilt vehicle, while others may offer broader cover or decline it. Requirements vary with title brand, state regulations, insurer underwriting and whether the car can be legally registered for road use. A salvage vehicle awaiting required rebuilding or inspection is not necessarily eligible for normal road insurance.
Do not pay for a salvage EV assuming a “cheap repair” will make it automatically insurable. Some repair costs, especially those involving high-voltage components, may require specialist assessment. Ask the insurer in advance: Will you insure this exact VIN and title brand after the state inspection? Can I buy collision and comprehensive? How will you value it after a future total loss?
Save the rebuilt-title paperwork and repair invoices. Where prior damage is material to the condition or valuation, disclose it fully when asked, rather than relying on a seller’s general description.
Does the factory battery warranty transfer to a second owner?
A high-voltage battery warranty is not the same thing as collision or comprehensive insurance. The U.S. Department of Energy’s Alternative Fuels Data Center describes EV maintenance considerations and notes common manufacturer battery warranty terms, but exact eligibility, years, mileage, transferability and capacity thresholds vary by manufacturer and vehicle.
Check the original in-service date and mileage, not just the model year. Ask the manufacturer or authorised dealer to confirm the remaining battery warranty for the VIN. A warranty can address specified defects or capacity conditions; ordinary ageing, wear or accident damage may fall outside it. Likewise, comprehensive insurance is not a free battery replacement programme.
For technical buying due diligence, our used EV battery state-of-health guide explains why an independently interpreted SoH reading can be useful; the percentage on its own does not establish insurer eligibility or prove a battery is defective. Consult our battery warranty explainer for model-specific warranty questions.
Why must you check an EV for open safety recalls?
The U.S. National Highway Traffic Safety Administration (NHTSA) provides an official VIN-based safety recall lookup. It can reveal unrepaired recalls associated with a particular VIN, although it may not include repaired campaigns or every very recent or older manufacturer action. A “0 unrepaired recalls” result is not a full maintenance history or a guarantee the vehicle has no defect.
Recall remedies are a manufacturer/regulator matter and should not be confused with auto insurance claims. An open recall does not necessarily mean a car is categorically uninsurable; whether it affects underwriting or use depends on the carrier, vehicle condition and any manufacturer safety instructions. See our EV battery VIN recall guide for the checking steps.
What coverage should you consider for an older EV?
Liability coverage
Liability insurance generally addresses covered injury or property damage you cause to others. Most states require minimum coverage, but the exact requirements differ. Legal minimums can be insufficient for a severe incident. Review limits and uninsured/underinsured motorist options applicable in your state.
Collision and comprehensive
According to the NAIC’s June 2026 coverage explanation, collision generally protects against covered damage from hitting another car or object, while comprehensive can address listed non-collision events such as theft, fire, flood and severe weather. Neither product should be treated as an automatic battery-degradation warranty.
For an older vehicle of relatively low value, examine whether the annual premium and deductible justify continuing physical-damage cover. A financed car may still require both coverages under the lender’s agreement. If you choose liability only, you may have no policy payment for physical damage to your own EV after a collision.
Roadside assistance and specialist towing
If a used EV stops due to a flat high-voltage battery, breakdown or accident, confirm towing and recovery terms. An older EV may need model-specific transport procedures. Follow the owner’s manual; avoid assuming the car can be towed on its driven wheels. Read our EV maintenance checklist for related ownership planning.
What does an insurer pay if a previously owned EV is totaled?
A standard market-value auto policy usually evaluates the vehicle’s value immediately before the loss, subject to contract language, state rules and deductions. It does not normally promise the price paid when purchased or the cost of a brand-new replacement. Prior damage, title branding, vehicle condition, mileage, exact variant and applicable market evidence may affect value.
If you owe more on the loan than the insurer pays for a covered total loss, review any optional guaranteed asset protection (GAP) product. GAP does not replace collision/comprehensive cover and may include exclusions. See our loan, lease and GAP insurance guide.
A practical 10-step checklist before you buy a used EV
- Obtain the full 17-character VIN and verify it matches the title and vehicle.
- Run an NMVTIS-approved title and insurance-loss history report; check relevant state DMV records too.
- Check NHTSA’s VIN recall tool and contact the manufacturer about outstanding repairs.
- Ask for an independent EV-qualified inspection, including visible high-voltage system condition and service records where available.
- Request battery health information but distinguish SoH estimates from warranty eligibility.
- Obtain written quotes for this exact VIN and the coverage you want.
- If the title is salvage or rebuilt, explicitly tell the insurer and ask about limits, inspection and valuation.
- For financed purchases, compare the lender’s minimum insurance requirements with insurer offerings.
- Verify warranty transferability and remaining battery coverage directly with the manufacturer.
- Keep the quote, history report, sales agreement, inspection notes, title documents and declarations page.
Bottom line
Insure the actual second-hand EV, not just the model name. The VIN, title history, prior damage, remaining battery warranty and insurer terms determine whether the car is a sound purchase and which coverages may be available. A vehicle history report and independent inspection are complementary; neither is a replacement for a confirmed written insurance quotation.
Official sources reviewed November 7, 2026: FTC — Used Cars; FTC — Buying a Used Car From a Dealer; NMVTIS — Vehicle History; NHTSA — Safety Recall Lookup; NAIC — Auto Insurance; NAIC — Electric Vehicle Insurance Rates; NAIC — Coverage Basics; U.S. DOE — EV Maintenance. General educational information, not financial, legal or vehicle-safety certification.
Sık Sorulan Sorular
Can I insure a used electric car with a salvage title?
It depends on the state's vehicle-registration rules and the insurer. Some may offer coverage after a rebuilt title and inspection, while others may refuse or limit collision and comprehensive coverage. Obtain a written VIN-specific answer before buying.
Is a used EV cheaper to insure than a new one?
Not always. Market value matters, but repair complexity, parts, driver profile, location and coverage affect premiums. Get comparable quotes for the exact used EV and coverage.
Does an EV battery warranty transfer to a second owner?
Transferability, remaining term, capacity thresholds and exclusions depend on the manufacturer and VIN. Ask the manufacturer to confirm your exact vehicle's warranty rather than assuming transfer is automatic.
Does a clean title guarantee the used EV has no accident or flood damage?
No. The FTC recommends a history report and an independent inspection because records may be incomplete and not every prior repair or accident appears in every report.

1 comment