Quick answer: In the United States, the standard FDIC deposit insurance limit is $250,000 per depositor, per FDIC-insured bank, for each qualifying account-ownership category. It is not $250,000 for every separate checking or savings account. Two single-owner accounts at the same insured bank are normally added together; deposits at separately insured banks are evaluated separately; and certain joint accounts are evaluated under a different ownership category.
The Federal Deposit Insurance Corporation’s consumer guidance sets out these rules, with ownership requirements and examples. This article explains the straightforward cases and provides a method to verify more complicated arrangements using the FDIC’s own calculators.
What the four parts of the limit really mean
Per depositor: coverage is measured according to the depositor and the ownership category, not simply by the name of an account product.
Per insured bank: one bank’s separately located branches are not separate insurance units. Deposits at another independently insured bank are evaluated separately, even if both banks use the same brand or share a parent company; verify the actual insured institutions.
Per ownership category: single-owner, qualifying joint and certain retirement accounts have separate rules. A person may have more than $250,000 insured at one bank if the accounts genuinely qualify for different ownership categories.
Deposit accounts only: the insurance applies to eligible deposits such as checking, savings, money market deposit accounts and certificates of deposit (CDs), subject to conditions. It is not a guarantee for stocks, mutual funds, crypto assets or investment annuities.
Example 1: $190,000 in checking plus $90,000 in savings
Assume one person owns both accounts individually, with no designated beneficiaries, at the same FDIC-insured bank. The deposits total $280,000. The applicable single-owner coverage is ordinarily $250,000, leaving $30,000 above the standard limit. Opening a third checking account at that same insured bank does not create another $250,000 of single-owner coverage.
This hypothetical example omits accrued interest and any unusual account ownership features. The FDIC’s EDIE frequently asked questions explicitly state that an individual’s single-owner checking account and CD at the same bank are combined for coverage.
Example 2: One depositor, two different FDIC-insured banks
Now suppose the same depositor holds $200,000 in a single account at Bank A and $200,000 in a single account at an independently FDIC-insured Bank B. Assuming no other relevant deposits, both balances fit within their banks’ respective $250,000 limits, so the combined $400,000 is insured. The key is that Bank A and Bank B must truly be different insured institutions, not two branch addresses or separate product labels of the same bank.
The FDIC’s BankFind Suite can identify the legal insured institution, its FDIC certificate details and its branches. Check this before assuming a fintech brand, marketplace app or two bank logos represent two separate insurers.
Example 3: A qualifying $400,000 joint account for two people
Suppose two people own a $400,000 joint deposit account at one FDIC-insured bank, have equal withdrawal rights and satisfy the FDIC’s qualifying joint-account requirements. Their shares are normally treated as $200,000 each. Each owner has up to $250,000 of joint-ownership coverage across their qualifying joint accounts at that bank, so this example’s full $400,000 can be insured if neither owner has other joint deposits that push their combined share beyond the limit.
However, opening multiple joint accounts with the same co-owner does not automatically multiply coverage. The FDIC EDIE guidance explains how it combines a co-owner’s shares of joint deposits at the same bank.
Example 4: Single and joint ownership at the same bank
Consider one depositor with $200,000 in a single-owner checking account and also a qualifying two-person joint account with a balance of $400,000. If each joint owner has $200,000 attributable to that joint account and neither has other relevant deposits, all these example amounts are below their respective limits. The individual $200,000 is in the single category; the individual’s separate $200,000 joint share is evaluated in the joint category. Qualifying ownership—not the number of accounts—is why coverage may exceed $250,000 for the same person at the same insured bank.
Real-life joint, trust and retirement structures require all relevant accounts and formal ownership records to be considered; use the official estimator rather than simply applying these examples to complex cases.
Does FDIC insurance cover a money market account?
A money market deposit account at an FDIC-insured bank is an insured deposit account subject to the ownership-category limit. A money market mutual fund is an investment product and is not an FDIC-insured deposit. Similar names can create a costly misunderstanding. Ask for the precise legal product type, issuing institution and disclosures before transferring money.
What if I use several branches of the same bank?
A main-street branch, an airport branch and an online account can all be deposits at the same FDIC-insured bank. Branches do not create independent FDIC coverage. Check the legal bank and FDIC certificate in BankFind when names, mergers or brands are confusing. The FDIC specifically states that different branches of a single insured bank are not separately insured.
Five-minute method: check your own coverage using EDIE
- List each bank’s exact legal name and confirm FDIC-insured status through the official BankFind tool.
- For each insured bank, list all checking, savings, money market deposit and CD balances you own or co-own, along with formal account title and beneficiaries where applicable.
- Identify the ownership category for each account: single, joint, certain retirement, trust or other applicable category.
- Open the FDIC’s Electronic Deposit Insurance Estimator (EDIE) and enter all applicable accounts at one bank before reviewing the result.
- Repeat the calculation for each other insured bank. If an ownership arrangement is unclear, contact FDIC or your financial institution for clarification.
EDIE is the FDIC’s own coverage estimator and is more appropriate for trust beneficiaries and other nontrivial structures than a simplified online blog calculation.
What FDIC insurance does not protect against
FDIC deposit insurance protects eligible balances if an FDIC-insured bank fails, within the coverage rules. It does not insure investments against market declines. It also does not serve as a general guarantee against every scam, theft or unauthorized transaction—other protections and dispute mechanisms may apply to those events. For banking-product terminology and consumer financial choices, see our credit-card interest calculation guide and our auto-loan interest-rate explainer. Those costs and protections are separate from deposit insurance.
Frequently missed detail: the limit is not per card or app
An app or debit card may display a branded account name, but deposit insurance depends on where funds are legally held, the ownership arrangement and whether all required conditions are met. A fintech or payment service is not necessarily an FDIC-insured bank. Check its legal banking relationship and terms using official disclosures; a marketing statement alone is not enough. If there is uncertainty about an intermediary holding funds, contact FDIC or the institution directly before assuming pass-through deposit insurance.
Sources and illustrated-photo attribution
Primary sources: FDIC: Understanding Deposit Insurance; FDIC EDIE Frequently Asked Questions; FDIC Electronic Deposit Insurance Estimator; FDIC BankFind Suite. All four worked examples use invented deposits and fictional Bank A/Bank B labels solely to illustrate the FDIC’s ownership-category rules. This is not individualized financial or legal advice.
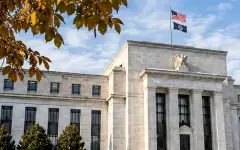
Cover: the entrance of the Federal Deposit Insurance Corporation in Washington, D.C., photographed May 3, 2025 by G. Edward Johnson / Wikimedia Commons, CC BY 4.0, unmodified. The photo depicts the real agency headquarters; it does not depict any of the fictional banks in the examples.
Sık Sorulan Sorular
Is the FDIC $250,000 limit per bank or per checking account?
It is per depositor, per FDIC-insured bank, for each qualifying ownership category—not per account. Single-owner checking and savings balances at the same bank are normally combined.
Does opening a second savings account increase FDIC protection?
Not by itself. Accounts at the same insured bank and in the same ownership category are aggregated regardless of account count.
Can a couple have $500,000 FDIC coverage in a joint account?
A qualifying two-person joint account can have up to $500,000 in aggregate coverage if each co-owner's share of all qualifying joint deposits at that insured bank remains within the $250,000 limit.
Are money market funds protected by FDIC insurance?
Money market deposit accounts at insured banks are eligible deposits, but money market mutual funds are investment products and are not FDIC-insured.