When does 2027 health insurance open enrollment start and end? For the federally operated HealthCare.gov Marketplace, Open Enrollment for 2027 coverage began November 1, 2026 and runs through January 15, 2027. To have Marketplace coverage start January 1, 2027, enroll or change plans by December 15, 2026 and pay your first premium. If you enroll between December 16 and January 15, coverage generally starts February 1, 2027, following payment and eligibility requirements. These dates are published by HealthCare.gov and the Centers for Medicare & Medicaid Services.
Last verified November 8, 2026. This guide is for U.S. individual and family health insurance purchased through the ACA Marketplace, especially states using HealthCare.gov. Some states operate their own exchanges and may set different dates or procedures. It is not a Medicare enrollment guide or a substitute for advice about an individual’s eligibility.
2027 ACA Marketplace open enrollment: exact federal deadlines
| Date | What happens on HealthCare.gov |
|---|---|
| November 1, 2026 | 2027 Open Enrollment opens: apply, renew or change Marketplace plans |
| December 15, 2026 | Deadline to select or change plans for a January 1, 2027 coverage start |
| January 1, 2027 | Coverage begins for eligible December 15 enrollees who pay the first premium |
| January 15, 2027 | Last day of the federally operated 2027 Open Enrollment window |
| February 1, 2027 | Coverage generally begins for eligible people selecting plans December 16–January 15 and paying the first premium |
These dates are not interchangeable. December 15 is the important deadline if a reader wants coverage from the beginning of January. January 15 is the final regular deadline to sign up through the federal Marketplace. Applications after Open Enrollment generally require a qualifying Special Enrollment Period, except for Medicaid and CHIP where eligible applicants can apply year-round.
Do all U.S. states have the same Marketplace enrollment dates?
No. The federal dates above are for the states that use HealthCare.gov. Other states operate state-based Marketplaces and may use different calendars, application tools or extensions. Before assuming the federal deadline applies, start at HealthCare.gov and enter your ZIP code or use the state’s official exchange site. The proper site may redirect you to your state’s Marketplace.
Be cautious about search advertisements or unsolicited calls promoting a supposedly mandatory paid enrollment service. Official Marketplace applications and eligibility checks are accessible through the government-approved process; people may also obtain free enrollment assistance.
How do I apply for 2027 coverage on HealthCare.gov?
- Visit the official HealthCare.gov homepage, or follow its route to your state’s official Marketplace.
- Sign in to your existing account or create one using the official website. New applicants and people renewing coverage should review their personal information.
- Provide accurate household details, including the people you expect to include in your tax household in 2027.
- Estimate your 2027 household income; the Marketplace assesses savings for the coverage year, not merely last year’s pay.
- Review any available premium tax credit or cost-sharing assistance shown after completing the eligibility application.
- Compare the actual plans available in your ZIP code, including monthly premium, deductible, provider network, prescriptions and maximum out-of-pocket spending.
- Select a plan, submit enrollment and follow your insurance company’s instructions for paying the first monthly premium. Applying alone is not always the final step to activate coverage.
HealthCare.gov lists online, telephone, trained in-person assistance, approved enrollment partners and mailed paper applications among its official application methods. A paper application has its own processing time; use the online or assisted process if a deadline is near.
What income should I enter for 2027 health insurance?
Estimate the income your tax household expects to receive during 2027. HealthCare.gov explains that Marketplace subsidies use a measure called modified adjusted gross income (MAGI). You may be asked about current monthly income while the application also requests an estimate for the entire coverage year. Include the household members who must be included under the application rules.
Use a good-faith estimate and update the application when your circumstances change. A large difference between your estimated and actual qualifying income can affect tax-credit reconciliation when you file your federal return. See HealthCare.gov’s official income and household guide for the types of income to count and whom to include.
How much will a 2027 Marketplace insurance plan cost?
There is no single nationwide premium. Costs depend on location, age, household size, plan choice and whether the applicant qualifies for premium tax credits or other savings. CMS published its 2027 plans and prices fact sheet on October 30, 2026, but its national summary statistics are not a personalized quote.
To see prices relevant to your household, use the official Marketplace plan and price preview: enter your ZIP code and the requested household and income estimates. HealthCare.gov emphasizes that preview prices are estimates and a submitted application provides the accurate eligibility and pricing information. Do not assume that an advertising banner with a $0 or $50 premium applies to everyone.
What costs matter besides the monthly premium?
The monthly premium is what you pay to keep coverage. It is not the only cost of care. When comparing two plans, check the following:
- Deductible: the amount you may need to pay for covered services before the plan shares certain costs, subject to its terms.
- Copayments and coinsurance: amounts or percentages you may owe when receiving covered care.
- Annual out-of-pocket maximum: a cap for qualifying in-network covered expenses, not necessarily including premiums or non-covered care.
- Provider network: whether your doctors, hospitals, facilities and pharmacies are included.
- Prescription coverage: whether specific medications are covered and the tier or requirements that apply.
- Coverage category and plan structure: the trade-off between premium level, cost sharing and provider access.
A cheaper monthly premium can sometimes be accompanied by a higher deductible or other costs. Examine each Marketplace plan’s Summary of Benefits and Coverage rather than comparing premiums alone.
Are premium tax credits available for 2027?
Some eligible Marketplace enrollees may qualify for a premium tax credit that lowers their monthly insurance bill. Eligibility and credit amounts depend on the applicant’s household size, expected income, and other applicable rules. The correct way to check is to complete a 2027 Marketplace application or use the official income and savings guidance.
Do not assume that a previous year’s tax credit will be the same in 2027. Eligibility rules and household circumstances may change. The additional pandemic-era subsidy expansions that affected earlier years should not be treated as automatically continuing without reviewing the current rules. Savings may also depend on whether a person is offered qualifying affordable coverage elsewhere.
What if I already have Marketplace coverage for 2026?
If you have a 2026 Marketplace plan, review your 2027 renewal notice and application rather than assuming all details and costs stay unchanged. HealthCare.gov advises existing customers to update estimated income and household information, confirm doctors and drugs, and review all 2027 plans. A plan may be discontinued, renamed or changed.
Automatic re-enrollment may occur in some circumstances, but it does not guarantee the same premium, benefits or provider network. HealthCare.gov says a current enrollee who takes no action by December 15 may be assigned to the same or a different plan, subject to renewal rules. See the official renewal and plan-change guide.
Can I get 2027 health insurance after January 15?
After the regular federal Marketplace window closes, eligible people may enroll or change plans if they qualify for a Special Enrollment Period (SEP). Examples can include losing qualifying health coverage, moving, marrying or having a child, with documentation, deadlines and state-specific rules. Some qualifying events permit a window of about 60 days, but not every event works identically.
Medicaid and the Children’s Health Insurance Program (CHIP) are different: people who meet their eligibility rules may apply year-round. Start with HealthCare.gov’s Special Enrollment, Medicaid and CHIP guidance rather than assume January 15 is a cutoff for every U.S. health program.
Is 2027 Marketplace open enrollment the same as Medicare open enrollment?
No. This guide concerns ACA individual and family Marketplace plans, not Medicare’s distinct enrollment periods. People eligible for Medicare or covered through an employer, a military plan or another government program should check that program’s own rules. Do not drop existing coverage without confirming a new policy’s effective date and whether any eligibility restrictions apply.
Common mistakes to avoid before December 15
- Waiting until January 15 while expecting coverage from January 1.
- Thinking that submitting an application is the same as paying the first insurance premium.
- Entering 2026 income without estimating the actual 2027 household situation.
- Ignoring provider networks, prescription coverage and out-of-pocket costs when comparing premiums.
- Assuming last year’s subsidy amount and plan design will automatically continue.
- Following a non-government enrollment link from an unsolicited message or sharing private financial information with an unverified intermediary.
Related guides and official sources
For independent coverage explainers browse our Health Insurance & Marketplace and Insurance sections. Readers also planning retirement may find our separate Social Security 2027 COLA notice guide useful; Social Security benefits and Marketplace premium tax credits are different programs and should not be confused.
Primary government references
- HealthCare.gov: Official 2027 enrollment deadlines
- CMS: Plan year 2027 Marketplace plans and prices fact sheet, October 30, 2026
- HealthCare.gov: Ways to apply and enroll
- HealthCare.gov: Preview local plans and prices
- HealthCare.gov: Renew or change an existing Marketplace plan
- HealthCare.gov: Income and household estimation
- HealthCare.gov: Special Enrollment, Medicaid and CHIP
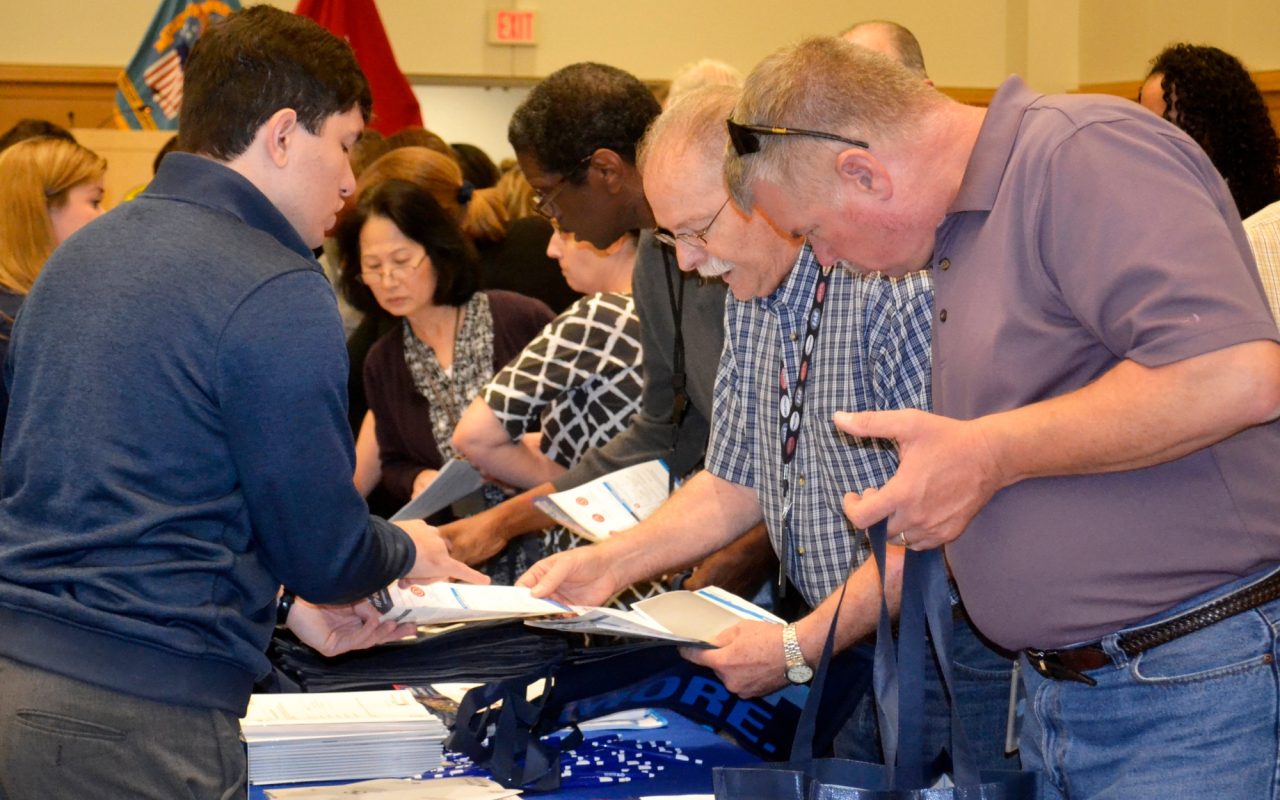
Illustrative archive photo: Employees and benefits representatives discuss health insurance choices during a 2018 federal employee benefits fair in Philadelphia. This real photograph illustrates comparing plan choices but does not show a 2027 HealthCare.gov Marketplace signup, and the federal employee health benefits program is separate from the ACA Marketplace. U.S. Defense Logistics Agency photo by Shaun Eagan, public domain, DVIDS image 4869379.
Sık Sorulan Sorular
When does HealthCare.gov open enrollment for 2027 end?
January 15, 2027 is the final day of the regular federally operated Marketplace Open Enrollment window.
What is the December 15, 2026 deadline for?
It is the HealthCare.gov deadline to enroll in or change a plan so coverage can begin January 1, 2027, provided the first premium is paid.
What happens if I enroll in January 2027?
For HealthCare.gov enrollment during December 16–January 15, eligible coverage generally begins February 1, 2027 after the required premium payment.
Are the 2027 health insurance enrollment dates the same in every state?
No. HealthCare.gov publishes federal dates, while state-operated Marketplaces may have different calendars. Verify your state's official exchange.
Can I get Medicaid after Marketplace open enrollment closes?
Yes. Medicaid and CHIP generally accept applications year-round for people who qualify.
Does the 2027 Marketplace application guarantee a certain premium subsidy?
No. Actual premium tax credits depend on household information, eligibility rules and the completed application.